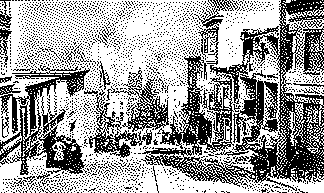
Rising Tide Management Investor Login →
Nearly four thousand years of pooled risk

Industries pushing humanity forward insure themselves.

For nearly 4,000 years, whenever an industry was novel and risky, the world wasn’t ready to insure it. So the industry banded together and insured itself - because Mutual insurance meant they could spread the risk and increase the upside for everyone trying to push the limits.

The Ancient Sea

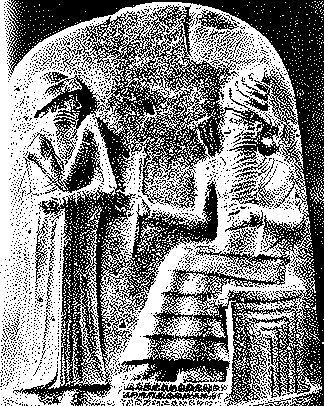
Black-and-white photograph of the relief at the top of the Hammurabi stele: a standing man in a round cap raises one hand before a seated, bearded god in a tall horned headdress who holds out a rod and ring.
Top of the Code of Hammurabi stele, c. 1754 BC, Louvre. Glass lantern slide, KU Leuven Libraries. Public domain.

A travelling trading agent who was robbed on the road could swear an oath before the god and be “free of obligation” to the merchant who had financed him (§103). If a robber was never caught, the community where it happened compensated the victim (§23). A farmer whose harvest failed in a storm or drought owed his creditor no grain that year (§48).

The loss of a robbed caravan fell on its backer, not on the man who carried it.

§103

The robbed agent “shall swear by God and be free of obligation”
L. W. King (trans.), The Code of Hammurabi (1910), Avalon Project, Yale Law School

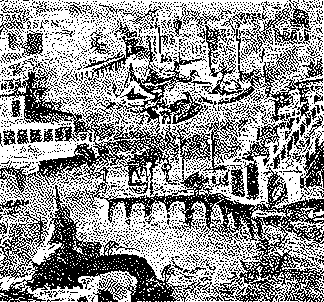
Roman fresco of a busy harbour painted in quick strokes: moored ships and small boats on blue-green water, colonnaded quays and a pier on arches, statues on tall columns, and buildings crowding the shore.
Harbour scene, Roman wall painting from Stabiae, c. 50–79 AD, Museo Archeologico Nazionale, Naples. Public domain.

Roman law preserved a rule from the seafarers of Rhodes: when cargo had to be thrown overboard to save a ship in a storm, the owner’s loss was made good by a contribution from everyone aboard, because it had been given for all. Shipping still runs on that rule, now called general average.

A loss taken to save everyone was shared by everyone.

Digest of Justinian 14.2.1 (Paulus), on the Lex Rhodia de iactu; today the York-Antwerp Rules

“By Policy of Assurance, the safety of Goods is Assured unto the Merchant; this is the Loadstone that draws him out to adventure.”

Francis Bacon · House of Commons · 7 December 1601
The Merchant Age

Panoramic painting of Genoa seen from the sea: the city rises in tiers around a crescent-shaped harbour lined with towers and quays, with dozens of sailing ships and galleys in the bay, all in warm, darkened varnish tones.
Cristoforo de Grassi, View of Genoa in 1481 (1597), Musei di Genova. Public domain.

In the 1340s Genoese notaries began recording contracts in which one merchant took on the risk of another’s voyage. Economic historians treat a deed of 18 March 1343 as the first modern insurance contract. In a better-known one, of 23 October 1347, the ship Santa Clara was covered from Genoa to Majorca, the cover disguised as a “free and friendly loan” that the insurer would pay only if the ship was lost.
By 1500 notaries from Barcelona to Venice had written thousands of such contracts, priced by the risk of the route.

7,000+

Insurance contracts written in Mediterranean ports, 1340–1500

Botticini, Buri & Marinacci, “The Beauty of Uncertainty”, JEEA 21(6), 2023Prudential, The Documentary History of Insurance (1915), Chart 206: the 1347 Santa Clara contract

In 1601 Parliament passed an Act concerning matters of Assurances amongst Merchants, to settle insurance disputes quickly. Its preamble explains what insurance does: when a ship is lost, no one man is undone, because the loss falls lightly on many instead of heavily on a few. On 7 December 1601 Francis Bacon presented the bill to the Commons, calling insurance “the Loadstone that draws him out to adventure.”
In Parliament’s words, merchants, “especially of the younger sort, are allured to venture more willingly and more freely.”

An Act concerning matters of Assurances amongst Merchants, 43 Eliz. I c. 12 (Statutes of the Realm, vol. 4 pt 2, p. 979)Townshend, Historical Collections (1680): “Mr. Bacon reports, about a New Bill for Insurances”

Oil painting of a three-masted East India Company ship heeling in a heavy green sea under shortened sail, two more ships close by, beneath a tall pale sky with grey storm clouds.
Charles Brooking, East Indiamen in a Gale, c. 1750s, Royal Museums Greenwich. Public domain.

Elizabeth I chartered the East India Company on 31 December 1600. Its first voyages were each paid for by their own subscribers, who took that voyage’s whole profit or loss. From 1613 investors subscribed to joint stocks that funded many voyages together, and with the New General Stock of 1657 the Company’s capital became permanent.

The Company never bought insurance on its own ships: in 1830 a London broker told Parliament it “never” did. It was the pool. By 1833 Macaulay could tell the Commons that this “joint-stock society of traders” commanded “a larger army” than the British government directly controlled.

A permanent pool of capital, spread across every voyage, became what the historian Tirthankar Roy calls “the world’s most powerful corporation.”

250,000

Soldiers in the Company’s army by the early 19th century

Z. P. Jennings, The English East India Company’s transition to a permanent capital, 1600–1685 (LSE PhD, 2024)Evidence of John Simpson, 17 June 1830, Journal of the House of Lords vol. 62T. B. Macaulay, “Government of India”, House of Commons, 10 July 1833National Army Museum, “Armies of the East India Company”Tirthankar Roy, The East India Company: The World’s Most Powerful Corporation (2012)

Hand-coloured aquatint of the tall, top-lit subscription room at Lloyd’s in the Royal Exchange: men in long coats and hats stand and talk among wooden counters and benches, with clocks on the far wall and a fireplace at right.
Thomas Rowlandson and Augustus Pugin, Lloyd’s Subscription Room, The Microcosm of London, 1809. Metropolitan Museum of Art, CC0.

By 1688, at Edward Lloyd’s coffee house on Tower Street in London, merchants had taken the next step. Instead of one backer carrying a whole voyage, many backers each took a slice of many voyages, writing their names under the risk; hence “underwriter”. A single lost ship no longer ruined anyone, and the market that grew from that room still insures ships today.

Spread a risk across enough members and enough voyages, and a loss that would sink one merchant becomes a cost every member can carry.

£181bn

Total assets of the Lloyd’s market, 31 December 2025

London Gazette, 1688: first recorded mention of Edward Lloyd’s coffee houseLloyd’s, Solvency and Financial Condition Report 2025 (market-wide balance sheet)

Etching of a packed church interior: the Rev. Alexander Webster in a white wig preaches from a high pulpit beside a thick stone column, facing tiers of listeners in wigs and bonnets, some dozing; signed ’IK 1785’, with a handwritten title beneath.
John Kay, Rev. Dr Alexander Webster preaching in the Tolbooth Church, Edinburgh, 1785. Public domain.

When a Church of Scotland minister died, his widow and children were often left with almost nothing. Two Edinburgh ministers, Robert Wallace and Alexander Webster, proposed that every minister pay a modest annual premium into one fund that would pay a pension to any widow it left behind. Webster collected data on ministers’ deaths and the families they left; Wallace priced the premiums from a life table; the mathematician Colin Maclaurin checked their sums.

The pooling is what made the widows better off. The premiums of ministers who left no widow went toward the pensions of those who did, and they were invested rather than simply passed through, so a widow could draw far more than her husband had ever paid in. The sums held, too: by one well-known account, the founders’ forecast of the fund’s capital in 1765 was out by a single pound. It was still paying out two and a half centuries later.

Alone, a minister’s modest savings would have left his widow little. Pooled with hundreds of others and invested, the same premiums paid her a pension that left her far better off.

£1

How far the founders’ forecast of the fund’s 1765 capital was out, by one well-known account

Fund established by Act of Parliament, 1744 (dated 1743 in some sources); published history 1743–1993Yuval Noah Harari, Sapiens (2014): the 1765 forecast of £58,348 against £58,347

In Parliament’s words, insurance means that merchants, “especially of the younger sort, are allured to venture more willingly and more freely.”

Preamble · An Act concerning Assurances · 1601
Steam & Steel

Oil painting of a three-masted sailing ship heeled over in a storm, its sails torn and rigging loose, driven through steep grey-green waves under a dark, lowering sky, with a second vessel faint in the distance.
Joseph Heard, The Lord Ashburton being driven by the gale, c. 1857–59. Public domain.

By the 1850s British shipowners faced liabilities their marine policies excluded: injury and loss of life aboard, and damage their ships did to others in collisions. Rather than carry those risks alone, in 1855 owners began forming mutual protection associations and insuring each other.

The clubs belong to the shipowners they insure. More than a century and a half later, the clubs of the International Group cover about 90% of the world’s ocean-going tonnage.

When the market won’t insure a risk, the people who carry it can, by pooling it among themselves.

~90%

Of the world’s ocean-going tonnage, insured by the shipowners’ own mutual clubs

International Group of P&I Clubs (tonnage share); first protection associations formed in Britain, 1855

Black-and-white photograph looking down a steep San Francisco street after the earthquake: damaged bay-windowed houses line both sides, debris and broken paving fill the road, residents stand watching, and huge clouds of smoke from the fire rise at the bottom of the hill.
Arnold Genthe, Looking down Sacramento Street, San Francisco, 18 April 1906. Public domain.

On 18 April 1906 an earthquake and three days of fire destroyed much of San Francisco. Insurers argued over whether each loss came from the quake or the fire; many delayed, and at least twelve went bankrupt. Lloyd’s tells how one of its leading underwriters, Cuthbert Heath, told his San Francisco agent to pay every policyholder in full.

By August insurers had paid about $50 million, and a newspaper reported it was enough for rebuilding to begin in earnest.

Claim money paid to rebuild a city. Foreign insurers paid out so much that gold flowed into the United States that autumn.

$180M

Paid by insurers on about $235M insured

Lloyd’s, “San Francisco 1906 earthquake”Insurance Journal, “Lloyd’s sees 1906 San Francisco earthquake as a turning point” (2006), citing the Insurance Information InstituteMorning Oregonian, 13 Aug 1906, p. 2Odell & Weidenmier, “Real Shock, Monetary Aftershock”, Journal of Economic History (2004)

“we were unable to obtain adequate life insurance due to the high risk nature of being an astronaut.”

Buzz Aldrin · Apollo 11 Lunar Module Pilot
The Atomic & Space Age

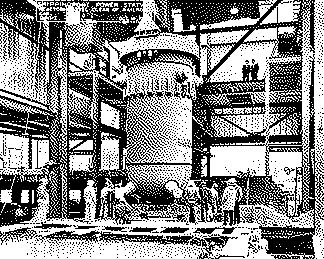
Black-and-white photograph of a tall cylindrical reactor pressure vessel suspended inside a steel-framed building under construction, workers in hard hats at its base and two men on a walkway above; a printed caption card at top left.
Shippingport Atomic Power Station, reactor vessel during construction, 10 October 1956. US Department of Energy. Public domain.

When the United States opened nuclear power to private companies, insurers were asked for $50 to $100 million of liability cover, when the largest market anywhere could write “twenty million dollars or less” on any one risk. In 1956 American insurers formed two pools that together offered $60 million per plant, and in 1957 the Price-Anderson Act put government indemnity on top.

In 1975 Congress went further: every large reactor in the country would chip in after an accident at any one of them. By 1982 that industry-funded layer had replaced the government’s.

Congress’s own researchers call the Act’s liability limits “crucial in establishing the commercial nuclear power industry.”

$158M

What every US reactor owes the shared pool, per accident at any reactor

R. H. Butler, “Liability Insurance for the Nuclear Energy Hazard”, Proceedings of the Casualty Actuarial Society (1959)NRC, 88 FR 60565 (5 Sep 2023): maximum deferred premium $158,026,000CRS, Price-Anderson Act, IF10821 (2025)NRC testimony, 24 May 2001 (1975 retrospective premium; government layer phased out 1982)

Fisheye colour photograph looking down the launch tower as the Saturn V rises past the camera on a column of fire, exhaust smoke spreading across the pad and the Florida coastline curving behind.
Apollo 11 liftoff, 16 July 1969, from a camera on the launch tower. NASA. Public domain.

Before Apollo 11, Neil Armstrong, Buzz Aldrin and Michael Collins signed hundreds of postal covers in quarantine. A friend had them postmarked on launch day and on landing day and gave them to the families, who could have sold them if the crew had not come home.

Aldrin later explained why: “we were unable to obtain adequate life insurance due to the high risk nature of being an astronaut.”

When the market couldn’t cover the risk, the people carrying it created an asset only they could make.

Buzz Aldrin, provenance letter, Bonhams Space History Sale, 5 May 2011, lot 121NPR Planet Money, “What The Apollo Astronauts Did For Life Insurance” (2012)

Oil painting of five of Nelson’s warships lying at anchor in a calm at Spithead with sails loosed to dry, among them HMS Vanguard, with the three-decker Victory firing a salute in the right foreground, small boats on the still water.
Nicholas Pocock, Nelson’s Flagships at Anchor, 1807, among them HMS Vanguard, the ship Jack Bogle named his company after. Royal Museums Greenwich. Public domain.

In his 1951 Princeton thesis, a young Jack Bogle concluded that actively managed mutual funds “can make no claim to superiority over the market averages.” The research that followed bore him out: a landmark study of 115 funds from 1945 to 1964 found that, on average, they could not beat a simple buy-and-hold of the market, and after their fees, their investors did worse.

In 1975 Bogle founded Vanguard on an unusual structure: the company is owned by its funds, and the funds by their investors, so there are no outside owners taking a profit. A year later it launched the first index fund for ordinary investors. Rivals called it “Bogle’s Folly”, and its first offering raised about $11 million.

Pooled, owned by its members and run for them, Vanguard’s investors kept more of the market’s return than most managers could earn for them.

$13.3T

Vanguard’s US fund assets, June 2026, from about $11 million in 1976

John C. Bogle, Princeton senior thesis (1951), as quoted in The Daily PrincetonianM. C. Jensen, “The Performance of Mutual Funds in the Period 1945–1964”, Journal of Finance (1968)S&P Dow Jones Indices, SPIVA U.S. Year-End 2024Vanguard, fast facts (US fund assets, 30 June 2026)

Long-exposure night photograph over Cape Canaveral: a bright arc traced by the rocket climbing away and a second streak where the first stage flew back to land, above a low horizon of lights.
ORBCOMM-2 launch and the first Falcon 9 first-stage return, long exposure, 21 December 2015. SpaceX, CC0.

On 21 December 2015 SpaceX landed the first stage of a Falcon 9 back at Cape Canaveral after putting 11 satellites into orbit. In August 2016 it licensed its own captive insurer, Final Frontier Insurance, to meet the FAA’s launch liability rules.

Its rockets and satellites it covers with its own balance sheet. SpaceX’s 2026 prospectus says it does “not typically obtain insurance coverage for our satellites, payloads, or launch vehicles, and as a result we bear the full financial cost of any such losses.”

Its own insurer for liability, its own balance sheet for the hardware: the company at the frontier carries the frontier’s risk itself.

The Planetary Society, “SpaceX sticks a rocket landing”, 21 Dec 2015Captive Review, “Elon Musk’s space programme opts for captive solution”, 6 Sep 2016FAA Chief Counsel to SpaceX, captive insurance under 14 C.F.R. § 440.9, 4 Aug 2016SpaceX, EU Prospectus approved by BaFin, 5 June 2026, risk factor 1.1.3

The next frontier

Venture capital is driving the world into the next century of great achievements. Each one of these might be more impactful to humanity than all prior venture-backed endeavors combined. This means, the time for mutual self-insurance has returned.

Humanity’s toughest and greatest achievements happen when the industries behind them insure their own risk.

As venture capital drives the world into its next century of great achievements, the industry is coming together to build what the market has refused to, and what is needed to achieve true greatness: a mutual self-insurance pool that will result in a permanent capital vehicle that can back humanity’s toughest endeavors for the next century and beyond.

Decades inside the room. Now opening the door.

Rising Tide was founded by a team with multi-decade backgrounds across both the public and private markets, collectively having managed multiple billions of dollars across market cycles, asset classes, and geographies.

We’ve worked inside the institutions that set the rules of modern finance. We understand why those rules exist, and exactly where they break down in the world that’s coming.

That combination of deep institutional knowledge and a willingness to build outside its constraints is what makes the products we build possible. Others aren’t building these products because the existing financial industry profits from startup equity staying locked up, illiquid, and exposed to catastrophic risk. We built this firm to be the financial partner that founders, their teams, and their backers have never had.

Battery Ventures The Boring Company Carbon Chain Citigroup Fifth Wall Goldman Sachs Neuralink

Advisors & Investors*

AngelList Anthropic Aon Aquarian Holdings Avocet Partners Berkshire Hathaway Specialty Insurance Chubb Citadel Citizens, Inc. CRC Group Deloitte Enduring Value Partners Google Marsh Odyssey Re Point72 Sensible Weather Shipyard Cascade Capital Thursday Ventures VitalityLife Work-Bench